Your Liability Exposure Probably Outgrew Your Policy Limits Years Ago
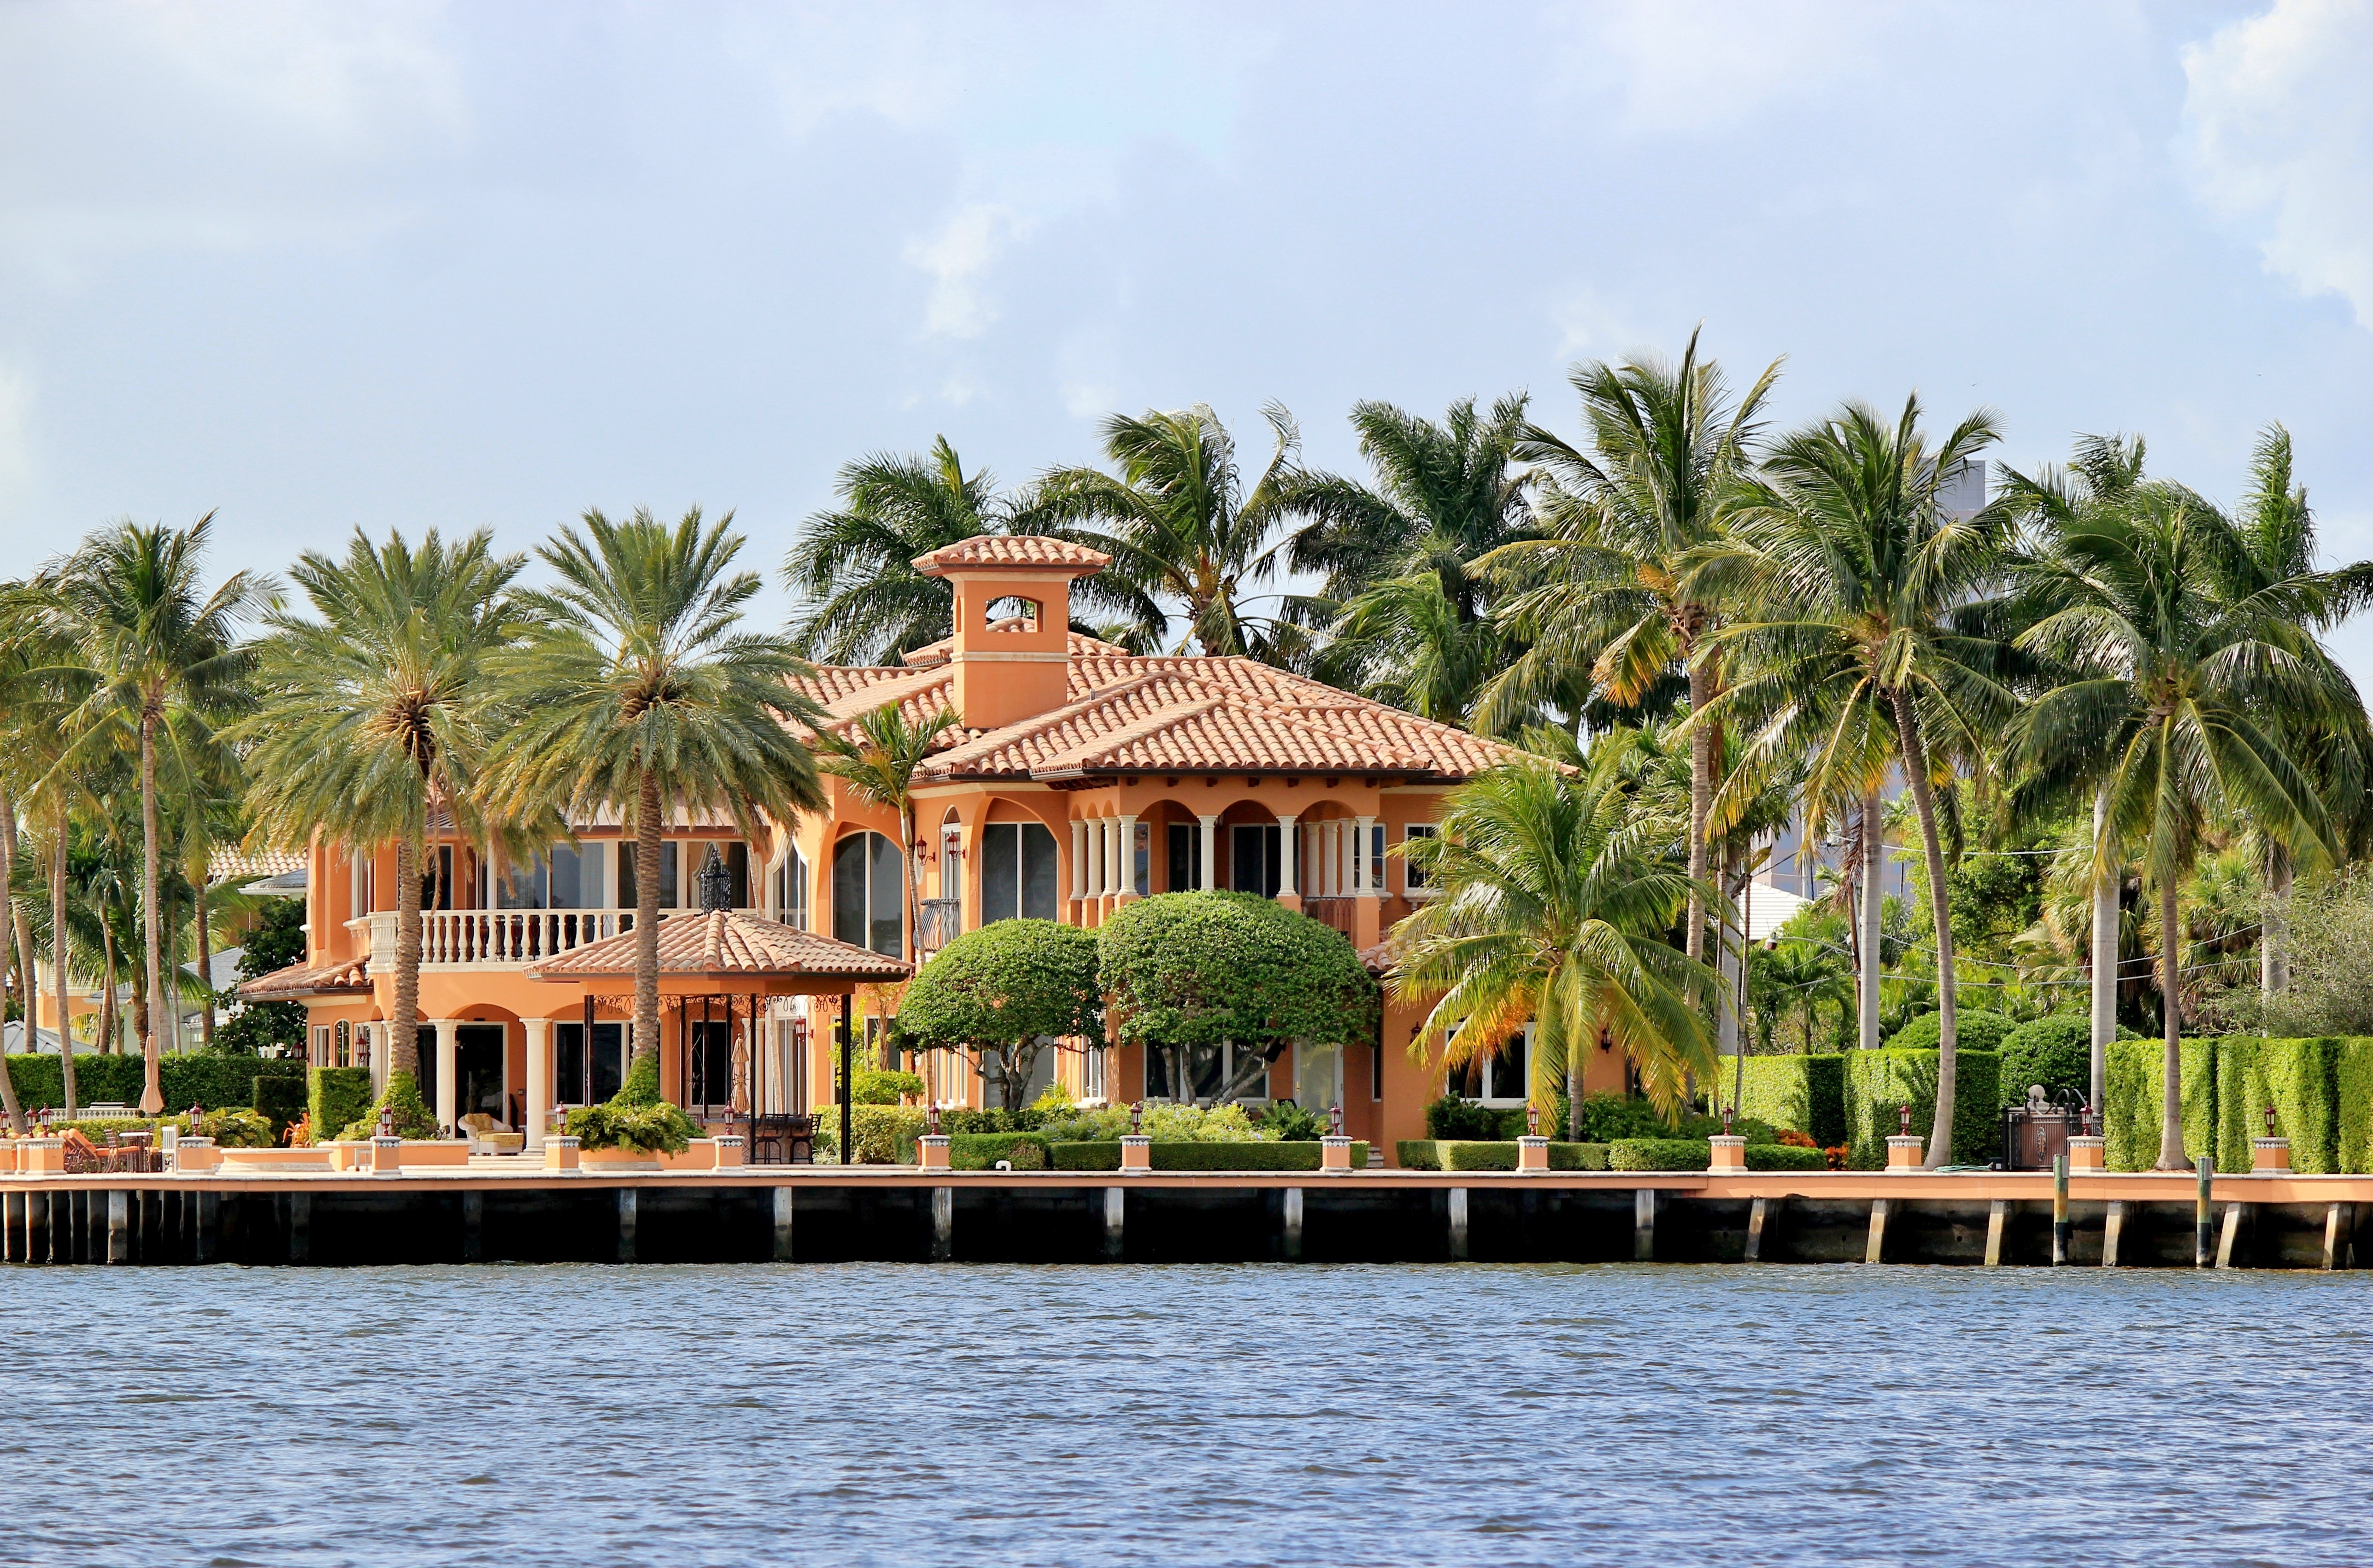
A single lawsuit can drain assets faster than most people expect. A guest slips by the pool, a boat brushes a dock in the Intracoastal, or a teenage driver is at fault for a serious accident. Any of these events can result in a claim that extends well past what a standard homeowners or auto policy covers. For families in Belleair and Belleair Beach who have spent decades building wealth, that gap between a policy limit and a jury verdict is where a personal umbrella and excess liability program earns its place in the portfolio.
Your Homeowners and Auto Policies Have a Limit
Standard homeowners policies typically cap personal liability between $300,000 and $500,000. Auto policies often carry similar limits per accident. However, carriers establish those figures for an average household, which does not include risks such as a waterfront home, a boat, a pool, or a driving-age teenager on the insurance. Florida recorded 16 nuclear verdicts (jury awards exceeding $10 million) in 2025, the second-highest total of any state in the country. A serious injury claim tied to a car accident, a swimming pool, or a social gathering at your home can exceed standard policy limits without much difficulty.
A Personal Umbrella Extends Protection, Subject to Its Terms
An umbrella policy sits above your homeowners, auto, and watercraft coverage and generally pays once you exhaust the applicable underlying limits. However, umbrella policies are not all alike, and many require the underlying policy to respond first, so an exclusion or limitation in your homeowners, auto, or watercraft coverage can limit or even eliminate umbrella coverage as well. Depending on the carrier, it may also extend protection to certain claims those policies do not typically cover, such as libel, slander, defamation, or false arrest. This coverage generally follows you and your family anywhere in the world, not just at your home address. As a result, an umbrella policy remains one of the most cost-efficient ways to add several million dollars of liability protection above qualifying underlying coverage.
Excess Liability Protects What Florida Law Does Not
Florida law grants unlimited dollar-value creditor protection to a primary residence, up to a half-acre in most municipalities, under the state's homestead exemption. That protection does not extend to investment accounts, business interests, rental properties, or future income, all of which remain exposed in a lawsuit that outpaces your insurance. Excess liability coverage fills that gap, standing between a judgment and the assets that homestead law leaves unprotected.
Where Waterfront Living Creates Additional ExposureWaterfront living in Belleair and Belleair Beach brings a specific set of risks. Private docks and seawalls, boats and personal watercraft, pools without safety barriers, and frequent guests all raise the odds of a liability claim. Additionally, household employees such as housekeepers, groundskeepers, or private caregivers add workers' compensation and employment liability questions that a standard homeowners policy never addresses.A Complimentary Review Can Show Where You Stand
Personal umbrella and excess liability coverage exists to help protect your assets from a lawsuit that exceeds your other policies, and may help cover the claims those policies were never written to include. Most families in Belleair and Belleair Beach already carry some version of it, but few know whether their limits still match what they have built. Contact SandStone Insurance Partners today for a complimentary consultation, and confirm you're covered before a lawsuit forces the question.